S&P 500 3-Month Seasonality Returns

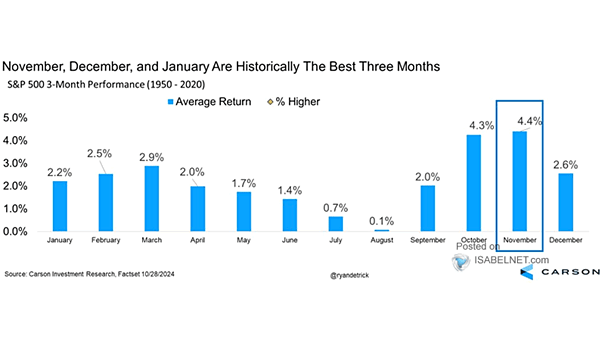
S&P 500 3-Month Seasonality Returns Will the U.S. stock market keep investors smiling? The three-month period of November through January has traditionally been the strongest for U.S. stock market performance. Image: Carson Investment Research
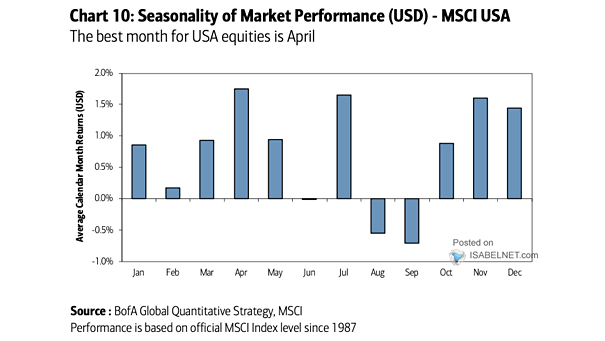
Seasonality of Market Performance – MSCI USA

Seasonality of Market Performance – MSCI USA August and September have historically been less favorable months for U.S. equities, with lower average performance compared to other months. Image: BofA Global Quantitative Strategy

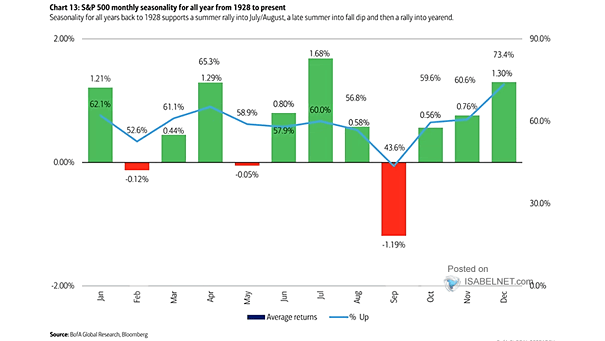
S&P 500 Seasonality Since 1928

S&P 500 Seasonality Since 1928 The seasonal trends observed since 1928 indicate a pattern where July and August typically see positive stock performance, followed by a dip in late summer and a rally into the year-end. Image: BofA Global Research

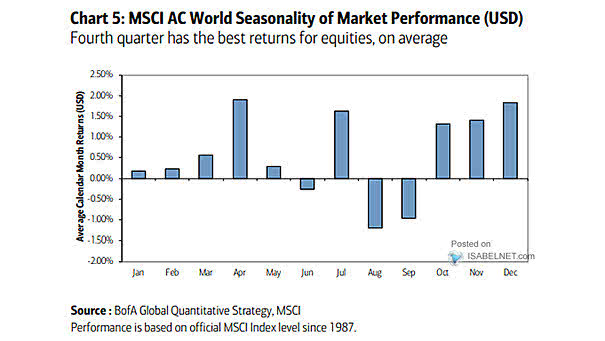
Seasonality Trends in MSCI AC World Index (Global Equities)

Seasonality Trends in MSCI AC World Index (Global Equities) July has historically been a strong month for global equities, offering opportunities for investors to capture potential gains. Image: BofA Global Quantitative Strategy

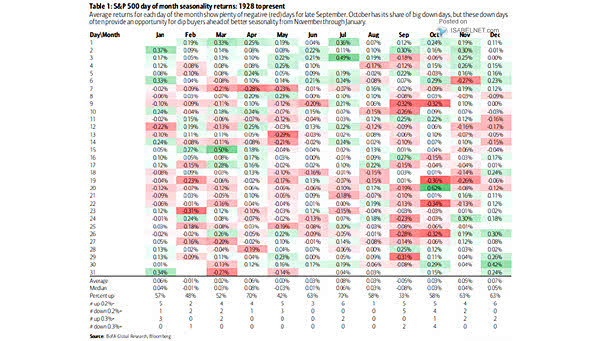
S&P 500 Day of Month Seasonality Returns

S&P 500 Day of Month Seasonality Returns Considering seasonality, it would not be surprising to see a bounce-back in the S&P 500 in early June, as historically, this period has demonstrated a trend of positive returns. Image: BofA Global Research

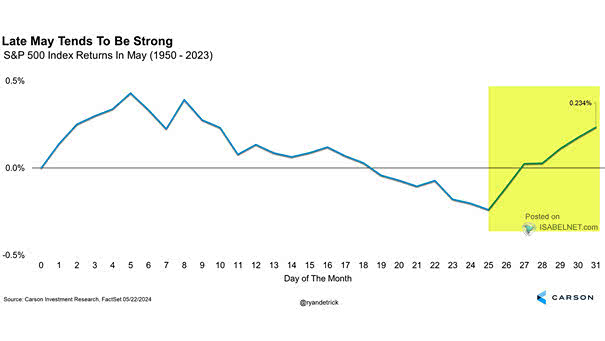
Seasonality – S&P 500 Index Returns in May

Seasonality – S&P 500 Index Returns in May The middle of May is historically a period of weakness for U.S. stocks, while the end of May typically exhibits strength. Image: Carson Investment Research
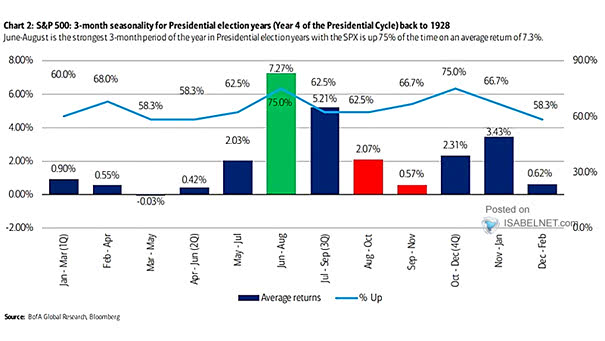
S&P 500 3-Month Seasonal Returns and Presidential Cycle Year 4

S&P 500 3-Month Seasonal Returns and Presidential Cycle Year 4 June to August historically shines during election years, as it represents the strongest 3-month period in the fourth year of the presidential cycle, up 75% of the time with an average return of 7.27% since 1928. Image: BofA Global Research

S&P 500 – Seasonality During Bull vs. Bear Markets

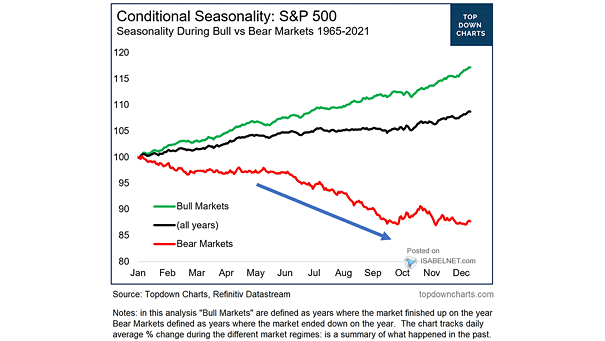
S&P 500 – Seasonality During Bull vs. Bear Markets The sell-in-May effect may be more relevant in bear markets. In bull markets, it may be seen as a missed opportunity for potential gains, given the positive momentum and upward trends typically observed in the market. Image: Topdown Charts

S&P 500 – Election Year Seasonality

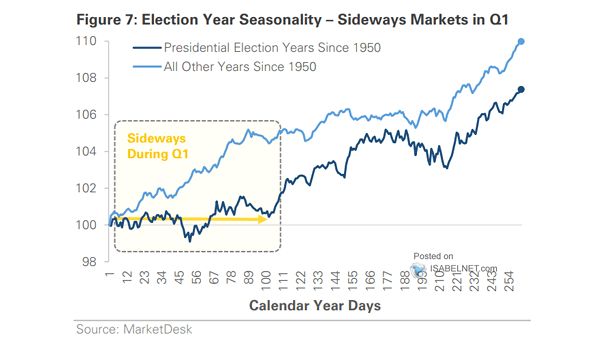
S&P 500 – Election Year Seasonality During election years, the S&P 500 tends to trend sideways in Q1. Investors are typically cautious about the potential outcomes of the upcoming elections and tend to adopt a more conservative approach. Image: MarketDesk Research

Performance – Russell 2000 vs. S&P 500 Seasonality

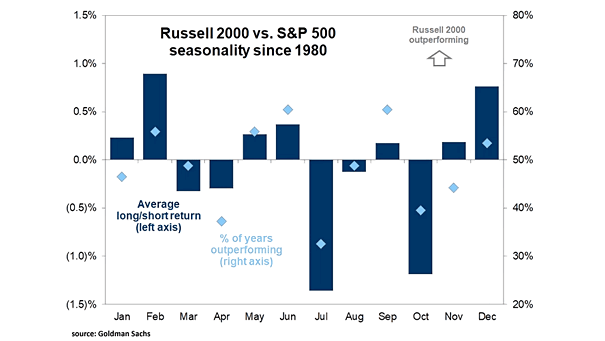
Performance – Russell 2000 vs. S&P 500 Seasonality Small caps historically tend to outperform the S&P 500 from December to February. Allocating a portion of the portfolio to small cap stocks during this time may benefit investors. Image: Goldman Sachs Global Investment Research