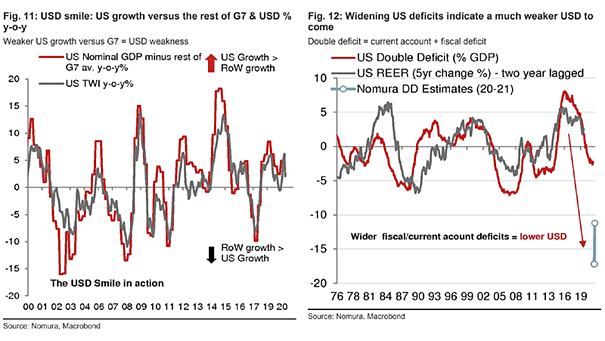
G7 Budget Deficits, Share of GDP

G7 Budget Deficits, Share of GDP The U.S. is running by far the largest budget deficit among G7 economies when measured relative to GDP, and projections show little improvement over the next few years. Image: Gavekal, Macrobond
G7 Inflation Average

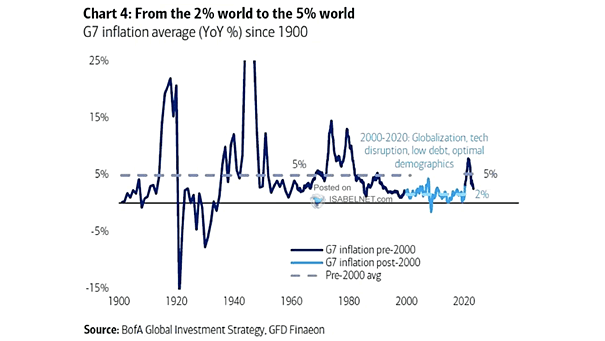
G7 Inflation Average Current projections and trends suggest a return to 5% inflation is unlikely in the near term, but long-term structural changes and unforeseen shocks could alter this outlook. Image: BofA Global Investment Strategy

Returns – G7 + China Free Liquidity and MSCI ACWI (Leading Indicator)

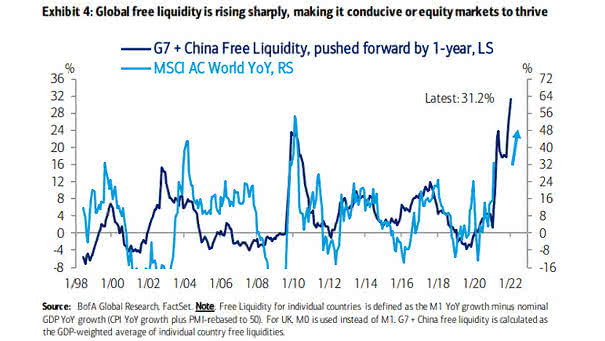
Returns – G7 + China Free Liquidity and MSCI ACWI (Leading Indicator) Global free liquidity continues to rise. When global free liquidity is above 10%, equity markets tend to perform well: the average next 12-month return is 23.4% with a hit ratio of 100% since 2009. Image: BofA Global Research

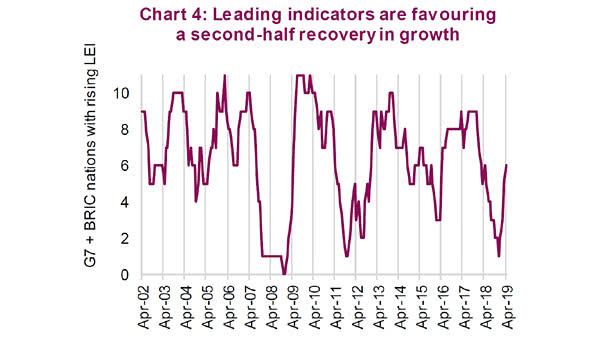
Second-half Recovery in Growth?

Second-half Recovery in Growth? Better economic data could extend the business cycle. Currently, G7 & BRIC leading indicators remain encouraging and suggest no imminent recession. Image: Richardson Wealth